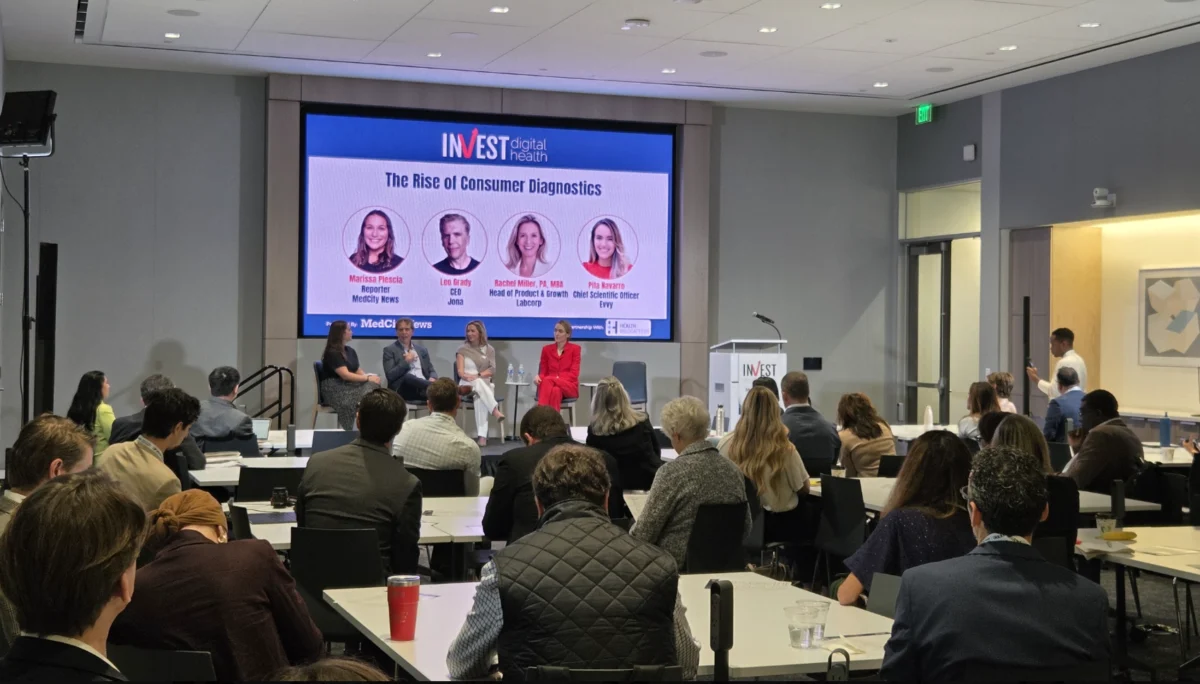
The traditional healthcare model, long characterized by a physician-centric approach to testing and data management, is undergoing a profound shift toward consumer-driven diagnostics. This evolution was the focal point of a high-level panel discussion at the MedCity INVEST Digital Health conference recently held in Dallas, where industry leaders gathered to dissect the drivers, challenges, and future implications of the burgeoning at-home testing market. The consensus among experts is that a confluence of technological readiness, regulatory shifts, and a fundamental change in patient expectations has moved diagnostic tools out of the clinical lab and directly into the hands of the consumer.
The Historical Trajectory of Consumer Diagnostics
While the current surge in direct-to-consumer (DTC) diagnostics feels like a recent phenomenon, the panelists noted that the seeds were sown decades ago. Leo Grady, CEO of the gut microbiome testing company Jona, highlighted that the desire for self-analysis is a long-standing human impulse. The timeline for modern DTC diagnostics began in earnest approximately 20 years ago with the emergence of companies like 23andMe, which introduced the public to the concept of genetic self-discovery.
In the mid-2010s, companies like Everlywell further democratized the field by making home-collection kits for common lab tests—such as cholesterol levels and thyroid function—mainstream. However, these early iterations were often viewed by the traditional medical establishment as "lifestyle" products rather than clinical tools. The shift from curiosity-based testing to clinically actionable diagnostics required a massive external catalyst, which arrived in the form of the global COVID-19 pandemic.
The COVID-19 Catalyst and the Compressed Adoption Curve
The pandemic acted as a forced experiment in healthcare delivery. According to the panel, COVID-19 did not just introduce a new disease; it fundamentally restructured the regulatory and behavioral landscape of diagnostics. Rachel Miller, head of product and growth at Labcorp, described this as a "compressed adoption curve."
Before 2020, regulatory hurdles made it difficult to ship clinical-grade tests across state lines or to allow patients to order tests without a direct physician referral. When the pandemic necessitated social distancing, federal and state regulators relaxed many of these restrictions to ensure the public could access testing from home. This regulatory "thaw" standardized the process of at-home sample collection and telehealth-based result interpretation.
Leo Grady emphasized that being confined to their homes made people more health-conscious and more comfortable with the idea of self-administered tests. The normalization of the nasal swab for COVID-19 paved the way for more complex tests involving stool samples, vaginal swabs, and finger-prick blood draws. This period proved that consumers could reliably follow instructions, collect samples, and engage with results via digital platforms, effectively debunking the myth that clinical testing must always happen within the four walls of a hospital.
Market Readiness and the Data Deficit
The rise of the sector is also attributed to a "primed market." Rachel Miller noted that for decades, healthcare providers have encouraged patients to "take control of their health." However, this encouragement was rarely accompanied by the necessary data tools. Patients were often left waiting weeks for lab results that were delivered in jargon-heavy reports they could not easily interpret.
The DTC diagnostic industry identified this gap and created a "product-market fit" by prioritizing user experience. By allowing patients to schedule their own tests, view results on intuitive mobile interfaces, and bypass the logistical hurdles of the traditional primary care office, companies have aligned their offerings with the expectations of the modern digital consumer.
Industry data supports this growth. The global home diagnostics market was valued at approximately $5.4 billion in 2022 and is projected to reach over $8.5 billion by 2030, growing at a compound annual growth rate (CAGR) of nearly 6%. This growth is driven by a rising prevalence of chronic diseases and an aging population that prefers home-based care solutions.
Specialized Diagnostics: Microbiome and Women’s Health
One of the most significant shifts in the DTC space is the move toward specialized, high-complexity testing, particularly in the realm of the microbiome. Pita Navarro, Chief Scientific Officer of Evvy, a company specializing in vaginal microbiome testing, highlighted a stark disparity in how diagnostic innovation has been applied.
Navarro pointed out that while the healthcare system can develop and deploy a vaccine for a novel virus within months, the standard of care for many women’s health issues remains archaic. In many OB/GYN offices, diagnosis still relies on "counting shapes under a microscope," a method that has not changed significantly in decades. This lack of innovation has led to a high rate of misdiagnosis in women’s health, where vaginal health issues are a leading reason for seeking medical advice.
The vaginal microbiome is a critical biomarker for various health outcomes, including the risk of cervical cancer, infertility, and the acquisition of sexually transmitted infections (STIs). By bypassing the traditional system, companies like Evvy are building massive, longitudinal datasets that were previously unavailable to researchers. These datasets allow for a more nuanced understanding of health that goes beyond the "presence or absence of disease" to focus on optimization and prevention.
The "Need" vs. "Want" Dichotomy in Modern Medicine
A recurring theme during the MedCity INVEST panel was the disconnect between what the traditional healthcare system provides and what patients actually desire. Leo Grady observed that in the legacy medical model, "diagnostics" was often treated as a "bad word." From the perspective of a health insurer or a busy physician, a new test might reveal a sub-clinical issue that requires further investigation, leading to increased costs and administrative burdens.
However, consumers view diagnostics differently. "People love data about themselves," Grady stated, noting that many individuals feel underserved by a system that only reacts to symptoms once they become severe. The DTC model caters to the "worried well" and those with chronic, unexplained symptoms who have "bounced around" between specialists without finding answers. By taking matters into their own hands, these patients are using diagnostics as a tool for self-advocacy.
Pita Navarro echoed this sentiment, suggesting that traditional doctors focus almost exclusively on what patients need—as defined by clinical guidelines—while ignoring what patients want—such as peace of mind, early detection, or a deeper understanding of their own biology. Consumer health companies operate at the intersection of these two categories, providing clinical-grade data that satisfies the patient’s desire for information.
Regulatory Challenges and the Path Forward
Despite the rapid growth, the consumer diagnostics industry faces significant headwinds, particularly regarding data privacy and clinical validity. As more sensitive health data is moved onto private servers, the risk of data breaches increases. Furthermore, the FDA has recently signaled a desire to increase oversight of laboratory-developed tests (LDTs), which many DTC companies rely on.
Critics of the DTC model argue that without a physician to interpret results, patients may experience unnecessary anxiety or make ill-advised medical decisions based on misunderstood data. To mitigate this, many leading companies have integrated "tele-consults" into their platforms, ensuring that every positive or complex result is followed by a conversation with a licensed medical professional.
Implications for the Broader Healthcare Ecosystem
The shift toward consumer diagnostics is forcing traditional players to adapt. Labcorp’s presence on the panel is a testament to this trend. As one of the world’s largest clinical laboratory networks, Labcorp is increasingly investing in direct-to-consumer channels, recognizing that the "patient-as-consumer" is here to stay.
The long-term impact of this shift could be a more preventative, data-driven healthcare system. If consumers can identify markers of chronic disease—such as pre-diabetes or gut dysbiosis—years before they manifest as clinical emergencies, the potential for cost savings and improved quality of life is immense.
Furthermore, the aggregation of consumer diagnostic data provides a goldmine for pharmaceutical research and public health monitoring. Large-scale, anonymized datasets from microbiome or genetic testing can help researchers identify new drug targets and understand how different populations respond to various treatments.
Conclusion
The MedCity INVEST Digital Health conference highlighted that the rise of consumer diagnostics is not merely a trend, but a fundamental realignment of the healthcare power dynamic. Driven by the lessons of the COVID-19 pandemic and a growing appetite for personal health data, consumers are no longer content to be passive recipients of medical information.
As companies like Jona, Evvy, and Labcorp continue to refine their offerings, the barrier between the "home" and the "lab" will continue to blur. While challenges regarding regulation and clinical integration remain, the trajectory is clear: the future of diagnostics is personal, portable, and patient-driven. By providing the tools for self-discovery and proactive health management, the consumer diagnostics industry is filling a void that the traditional healthcare system has long ignored, ultimately leading to a more informed and empowered patient population.

